Steve Finn on Franchise Recruitment to Business Broking
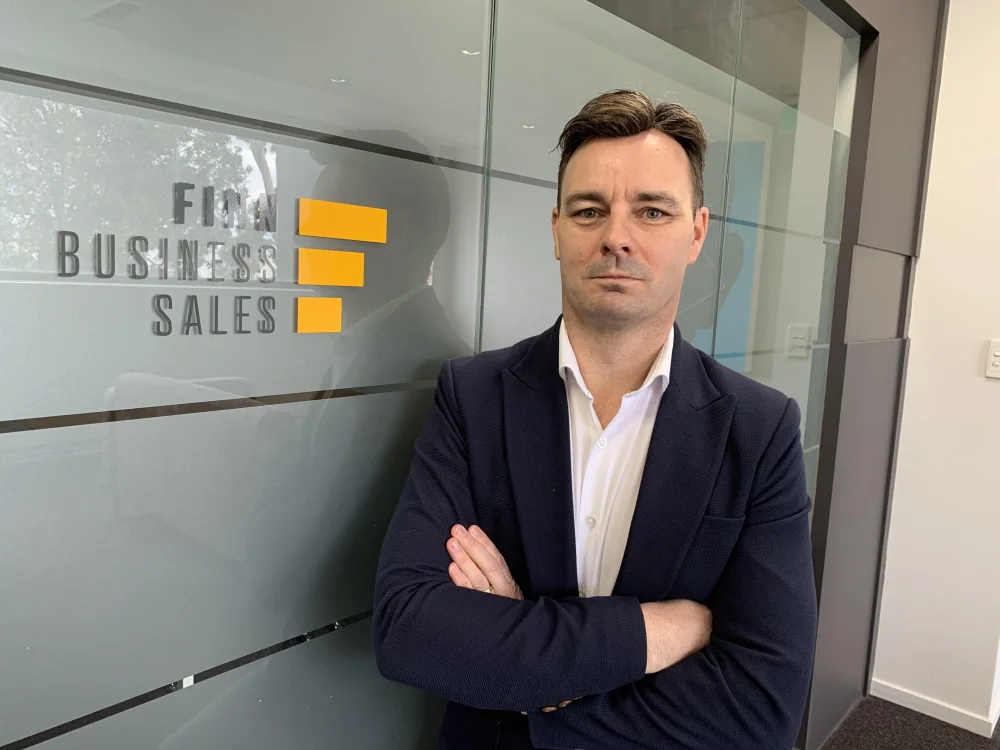
Bsale's Vanessa Lovie-Yousaf first met Steve Finn and Len Ferguson in 2011, when the pair were running a franchise brokerage across Western Australia and Queensland.
Their business, the Finn Group, started out in franchisee recruitment before moving into independent business sales. It later grew into Finn Business Sales, with mergers and acquisitions and financial planning services operating across several states.
Steve spoke with Bsale about how he and Len got started, what makes a good broker, and the mistakes business owners make when it comes time to sell.
Starting in Franchising
Steve says the move into business broking happened almost by accident.
"We came into the business broking world sort of accidentally because we actually started off in franchisee recruitment. That was our specialty and we did that for the first seven years. At that point, we had never sold an independent business."
Specialising in franchising gave them a niche, and the work kept coming.
"We were sort of the only ones specialising in franchising. So then a lot of the franchisors used us and then their franchisees used us, and we got quite a bit of exposure from there. And then we decided, okay, well, maybe we should start to sell independent businesses as well."
That shift into general business broking began in 2012.
Franchising appealed to them because of the professionalism of the systems and the volume a single relationship could bring.
"Working with a franchisor like The Coffee Club, where we've done a lot of work with them, and say, Boost Juice, you get one client, but you can then get 10 listings or 15 listings a year from one client."
Two States, One Brand
In the early days, the business was just Steve and Len. The two had met in Victoria, then moved to different states.
"I wanted to move to Perth, which I did. He wanted to move to Brisbane, which he did. Then I operated in Perth and Len operated in Brisbane and we just kind of shared the same website and the same forms and documents and built the business that way."
As franchisors started asking for help in other states, they had to decide how to grow.
"We thought we would either have to employ a lot of people in all the other states or we could turn our business into a franchise itself and then have other people open up in the other states and just use the same brand like we were doing really. So it just sort of evolved into what it is today."
Their background in franchising made the decision easier, but Steve is realistic about what a brand can and can't do for a new broker.
"It's a hard industry to make it in. The failure rate is a lot less than the general person who might start as a broker. The systems, branding and training make it a lot easier. But there's no guarantees."
Brokers Have to Be Able to Sell
When it comes to bringing new brokers into the business, Steve says financial knowledge on its own isn't enough.
"You'd see a lot of people who are kind of finance people, accountants, all that sort of stuff. But really, that doesn't get them far. You've got to be able to sell your services to the business owners. Sell yourself as a trusted advisor to the seller. Because if you're not getting listings, it really doesn't matter how good you are. It doesn't matter how much you know about valuations if you've only got one listing. The biggest thing is being able to sell, sell, sell."
What Sellers Should Look For in a Broker
For business owners choosing a broker, Steve looks at two things. The first is how organised and professional the broker is.
"I would look for someone that's really organised and really good at follow-up and really professional. In the information they give you, how they present themselves and if you can contact them. If you can, organise a meeting and they can give you a presentation about what they do."
The second is marketing.
"We monitor buyer enquiries and we're proactively making sure we get enough enquiries for each listing. Because if you are listed with them, but they're only using a small website or they might have a Facebook page, but it looks pretty average, you won't get many enquiries."
Why Buyers Should Get to Know Brokers
Steve believes buyers often miss opportunities by searching online and leaving it there.
"The way buyers generally behave is they just search around for things and put an enquiry in but don't engage very well, or very much, with a business broker really. I would suggest buyers look for a number of business brokers, talk to them on the phone and find someone who is really professional. Meet with them. Talk to them every few weeks, just to say, hey, anything new?"
At the time of the interview, Finn had around 500 businesses on the market and expected about another 200 to come on board over the following few months. Steve says buyers who stay in contact with brokers can hear about businesses before they're advertised.
It also separates serious buyers from the rest.
"You sort of make yourself stand out rather than just everyone who just submits an online enquiry. Then they disappear. That's what brokers call a tyre kicker."
The Price Problem
The biggest mistake Steve sees sellers make is overpricing.
"Thinking that the business is worth more than what the market says someone will pay. It's not their fault. They just don't know. They think, I need $400,000 to retire, but the business is only worth $200,000. Or, I paid $400,000 so I want $400,000 back, but they overpaid at the time unfortunately. Or since they bought it, it has gone downhill a little bit or they've had a couple of bad years."
Unrealistic expectations can stall a sale from either side.
"A stubborn seller is one that won't budge on their asking price and then they just never really sell. A stubborn buyer is one that makes an offer on a $500,000 business for $250,000 and is always going to make low offers. So a stubborn buyer will never be able to buy anything and a stubborn seller will never be able to sell their business."
When an overpriced business doesn't sell, the seller often blames the broker.
"They'll come to us and I'm sure they do this with us too. They blame the last broker, and try to get a new broker to sell the overpriced business."
His advice to owners is to choose carefully and then back the broker they choose.
"I wouldn't just select anyone. I'd find a really good one and then I'd say to them, okay, so you're about to go and get me $500,000, so what do you need? It's a team effort. I'll give you what you need and then you go get me my $500,000."
Don't Wait Until You've Had Enough
Steve tells sellers to expect the process to take time.
"It generally takes on average about six months from the time you go on the market, to finding the new owner, to handing over the keys. It might happen in three months, might be nine, you really don't know. I tell everyone you've just got to have in your mind that it will take six to 12 months."
He doesn't believe there is a best time of year to sell. Enquiries tend to rise in January as people reflect over the holidays, but that doesn't necessarily mean more businesses change hands.
"Honestly, if I had a business I was selling, I would just sell whenever I was ready. I wouldn't think, I'll wait until a certain month or I'll wait until the end of the financial year."
The risk is leaving it too late. Steve describes a familiar pattern. An owner lists at $300,000, gets frustrated after six months and drops to $200,000, then later drops again to $150,000.
"The problem is, they waited too long to list it for sale in the first place. They've given away like $100,000-plus just because they were frustrated. Whereas you're better to get in when you're just starting to think of it, rather than get to the point where you're completely frustrated."
Price cuts can also work against the seller.
"You'd be amazed how often we have to talk the client out of reducing the price of their business. If you think about it, I'll come to you and I go, oh, I've got this business making $150,000 and look, the owners just reduced the price twice and you can buy it for a hundred. You're going to go, what's wrong with it?"
Not Like Selling a House
Steve says business owners often drop their price more readily than homeowners because a business they want to leave is a daily burden.
"Once you decide you want out, you've got pain every day. You've got to get up. You've got to go there, you've got to unlock the door. You might be having troubles with the staff. You might be fighting with the chef."
Most people also have little experience selling a business.
"You might sell one or two in your life, if that."
That's why much of a broker's job is preparing the client for what's ahead.
"Half the stuff we do is coaching the clients into understanding what is involved. We do it every day, but from their side they don't. So a lot of what we do goes into educating, how this works, how that works. If we haven't sold it within two months, don't freak out. That's just normal."
Originally Published 2020. Updated 22 Oct 2026 to new style
Tags: business broker tips selling
About the author
Vanessa Lovie-Yousaf
CEO Bsale Australia
Vanessa Lovie-Yousaf is the CEO and manager of Bsale.com.au, one of Australia’s most trusted business for sale marketplaces since 2000. With 15 ...


