How to Buy a Business in Queensland
Buying a Business in Queensland. Image: Cairns North Queensland.
Queensland is one of the busiest markets for business buyers on Bsale.
Buyer enquiries in the state are growing faster than almost anywhere else in Australia, and the choice runs from Brisbane service businesses to Gold Coast cafes, Sunshine Coast lifestyle businesses and high-value industrial operations in Mackay and Central Queensland.
The opportunities differ a lot depending on where you look. So do the costs, the buyers you are competing with and the questions you need to ask before signing.
This guide walks through how to buy a business in Queensland, from setting your budget to settlement. It draws on Bsale marketplace data and on interviews with Queensland business brokers featured in the Bsale eMagazine.
If you are new to buying a business, start with our guide to buying a business in Australia, then use this guide for the Queensland detail. When you are ready to look, browse businesses for sale in Queensland.
Queensland's Business Market at a Glance
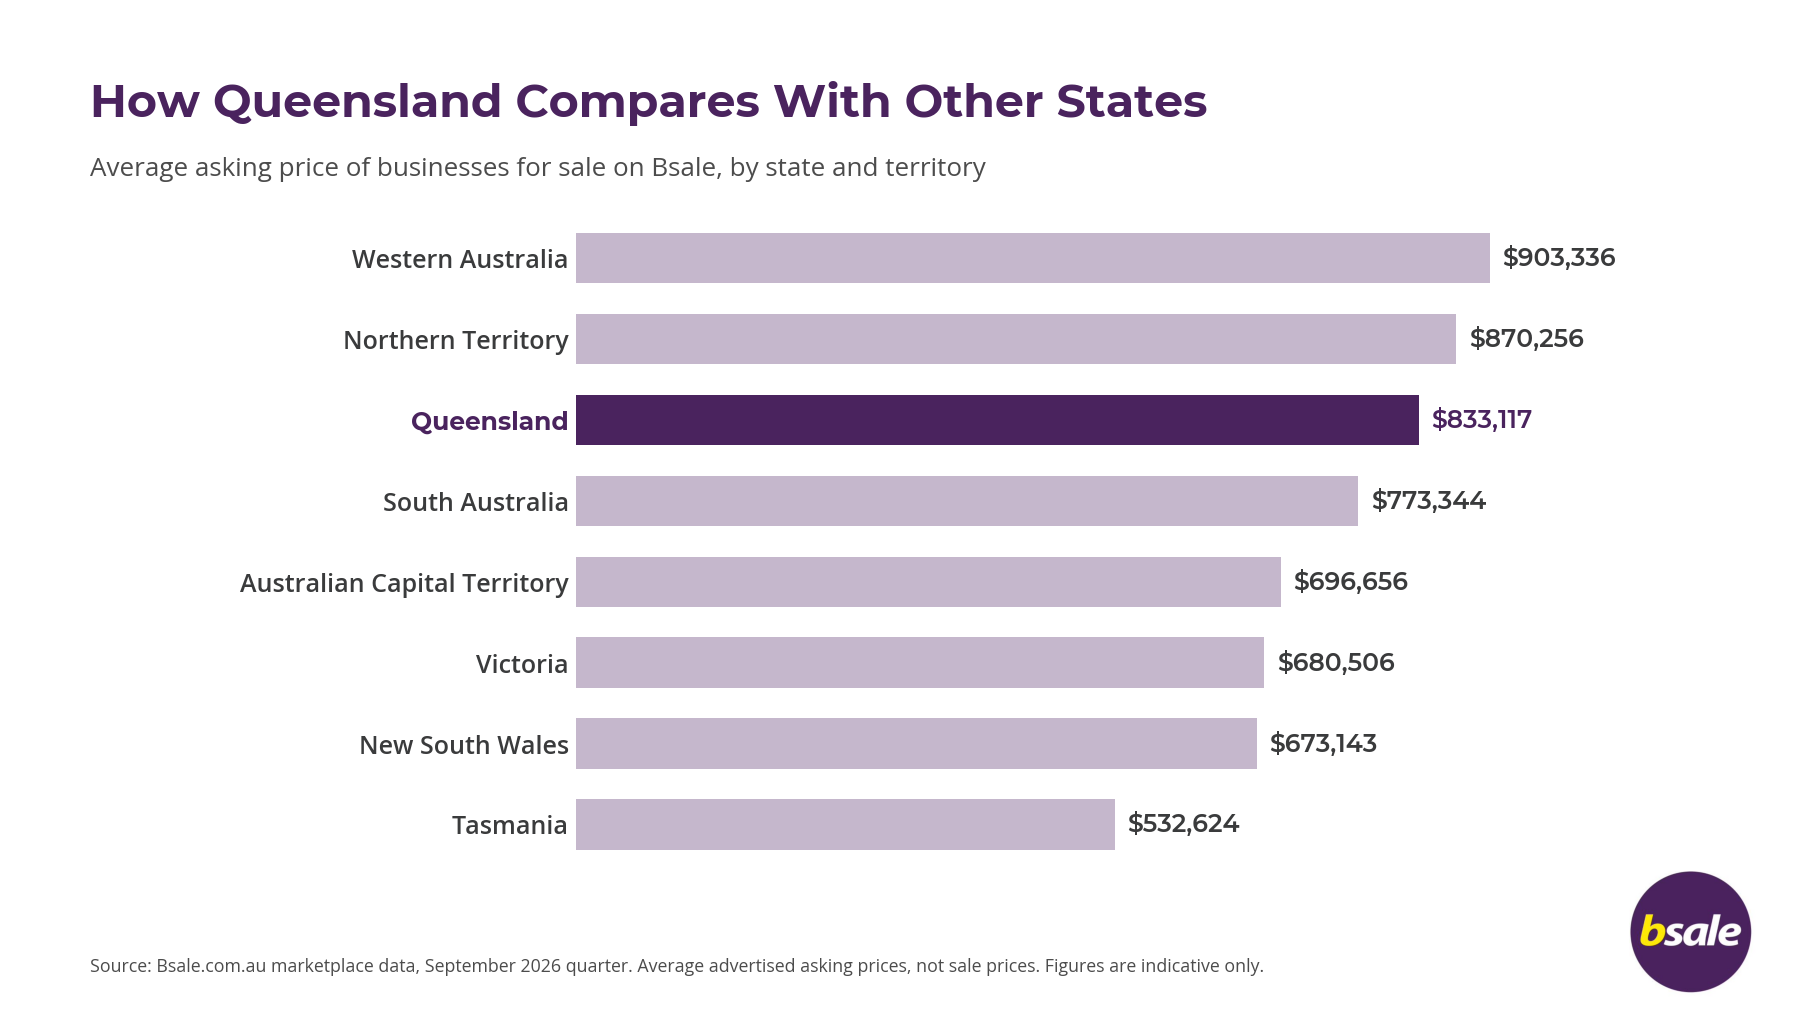
According to Bsale marketplace data for the September 2026 quarter, businesses for sale in Queensland carried an average asking price of $833,117. That was the third highest of any state or territory, behind Western Australia and the Northern Territory.
Buyer Demand Is Rising Fast
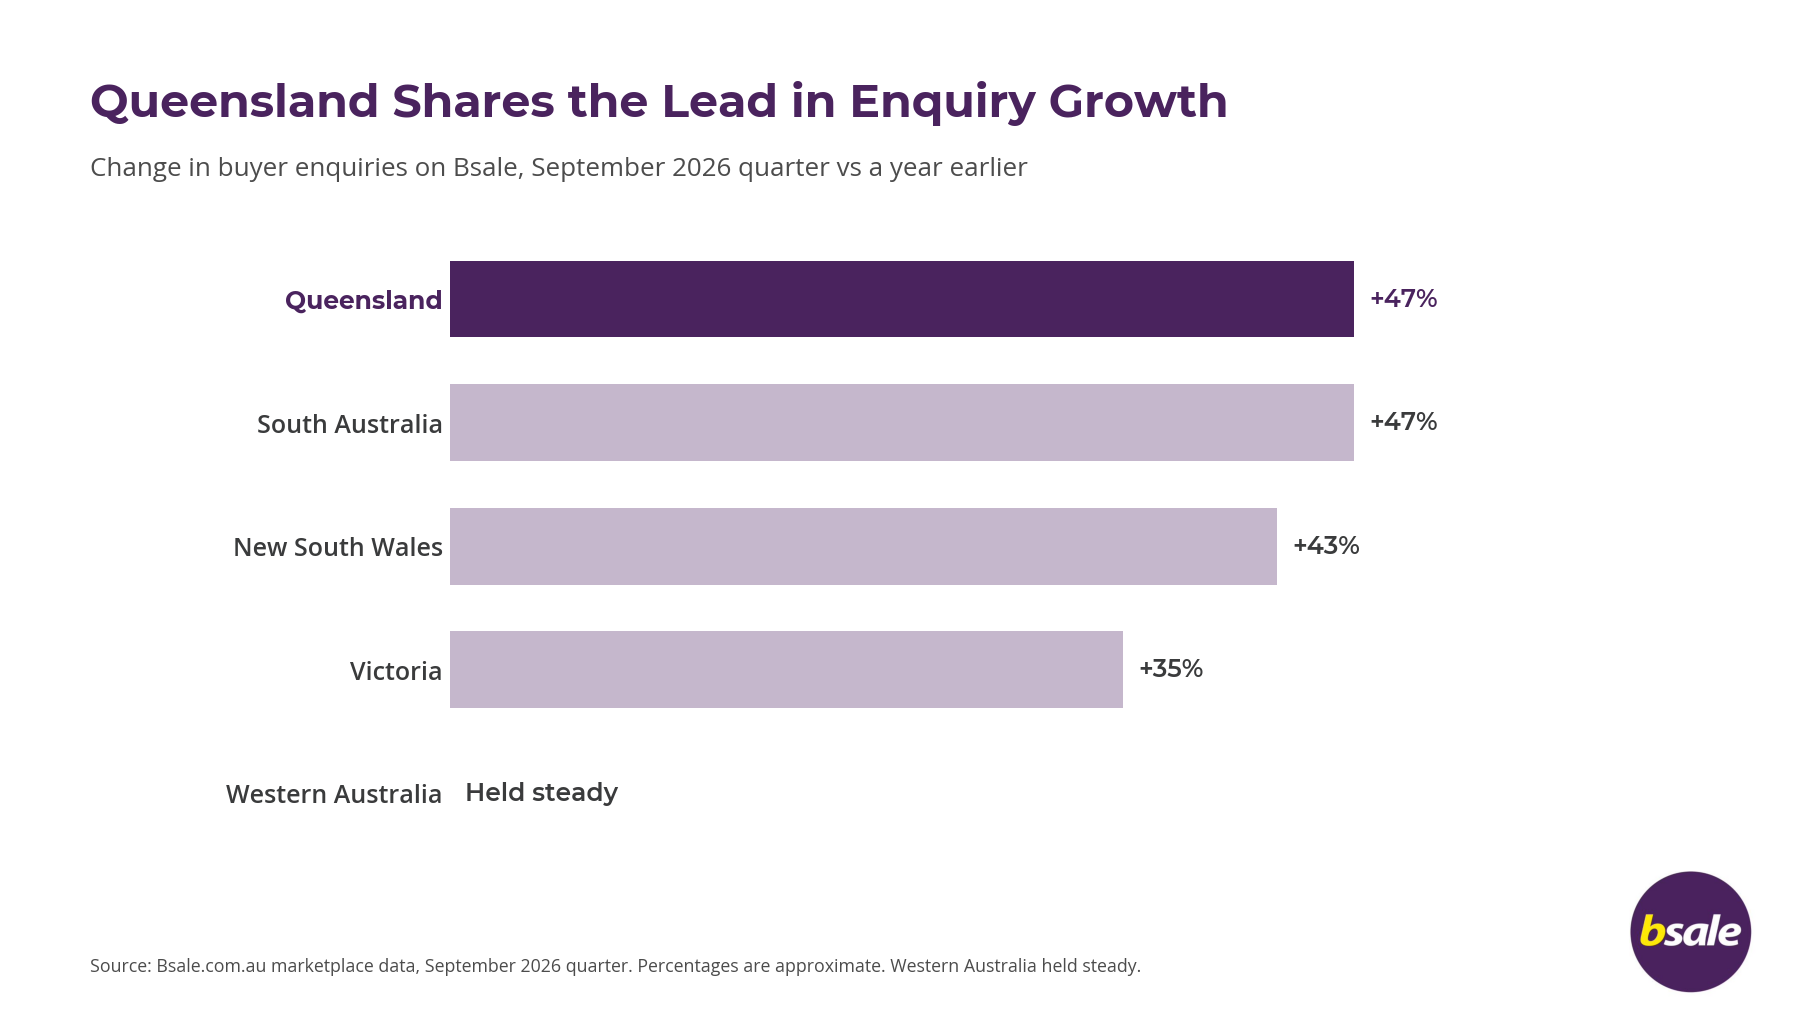
Enquiries rose about 47% on a year earlier, jointly the strongest growth of any state, and about 38% on the June quarter, the strongest quarterly momentum in the country.
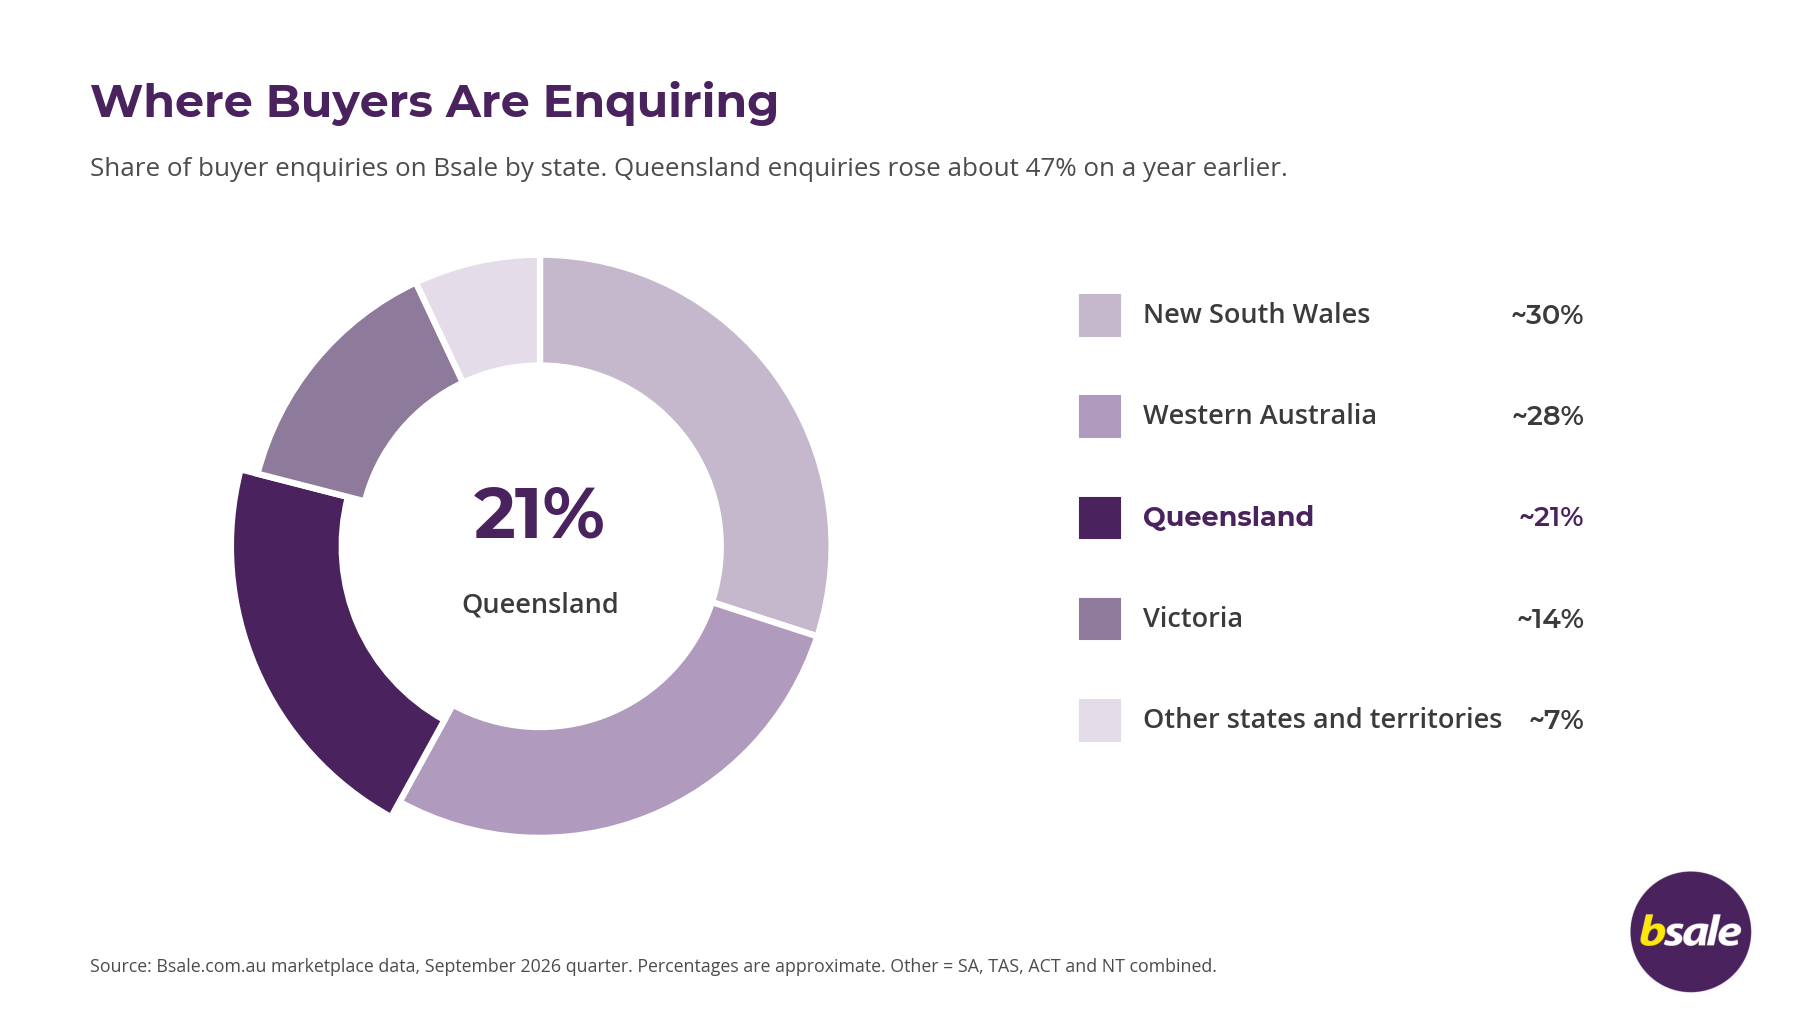
Queensland attracted about 21% of buyer enquiries on Bsale in the September quarter.
The Gold Coast was one of the areas with strong buyer interest. For more on how Queensland buyers are behaving, read Queensland Buyers Remain Active, But More Selective.
Brisbane, the Coasts and the Regions
The Queensland market is spread across several distinct regions, each with a different mix of businesses.
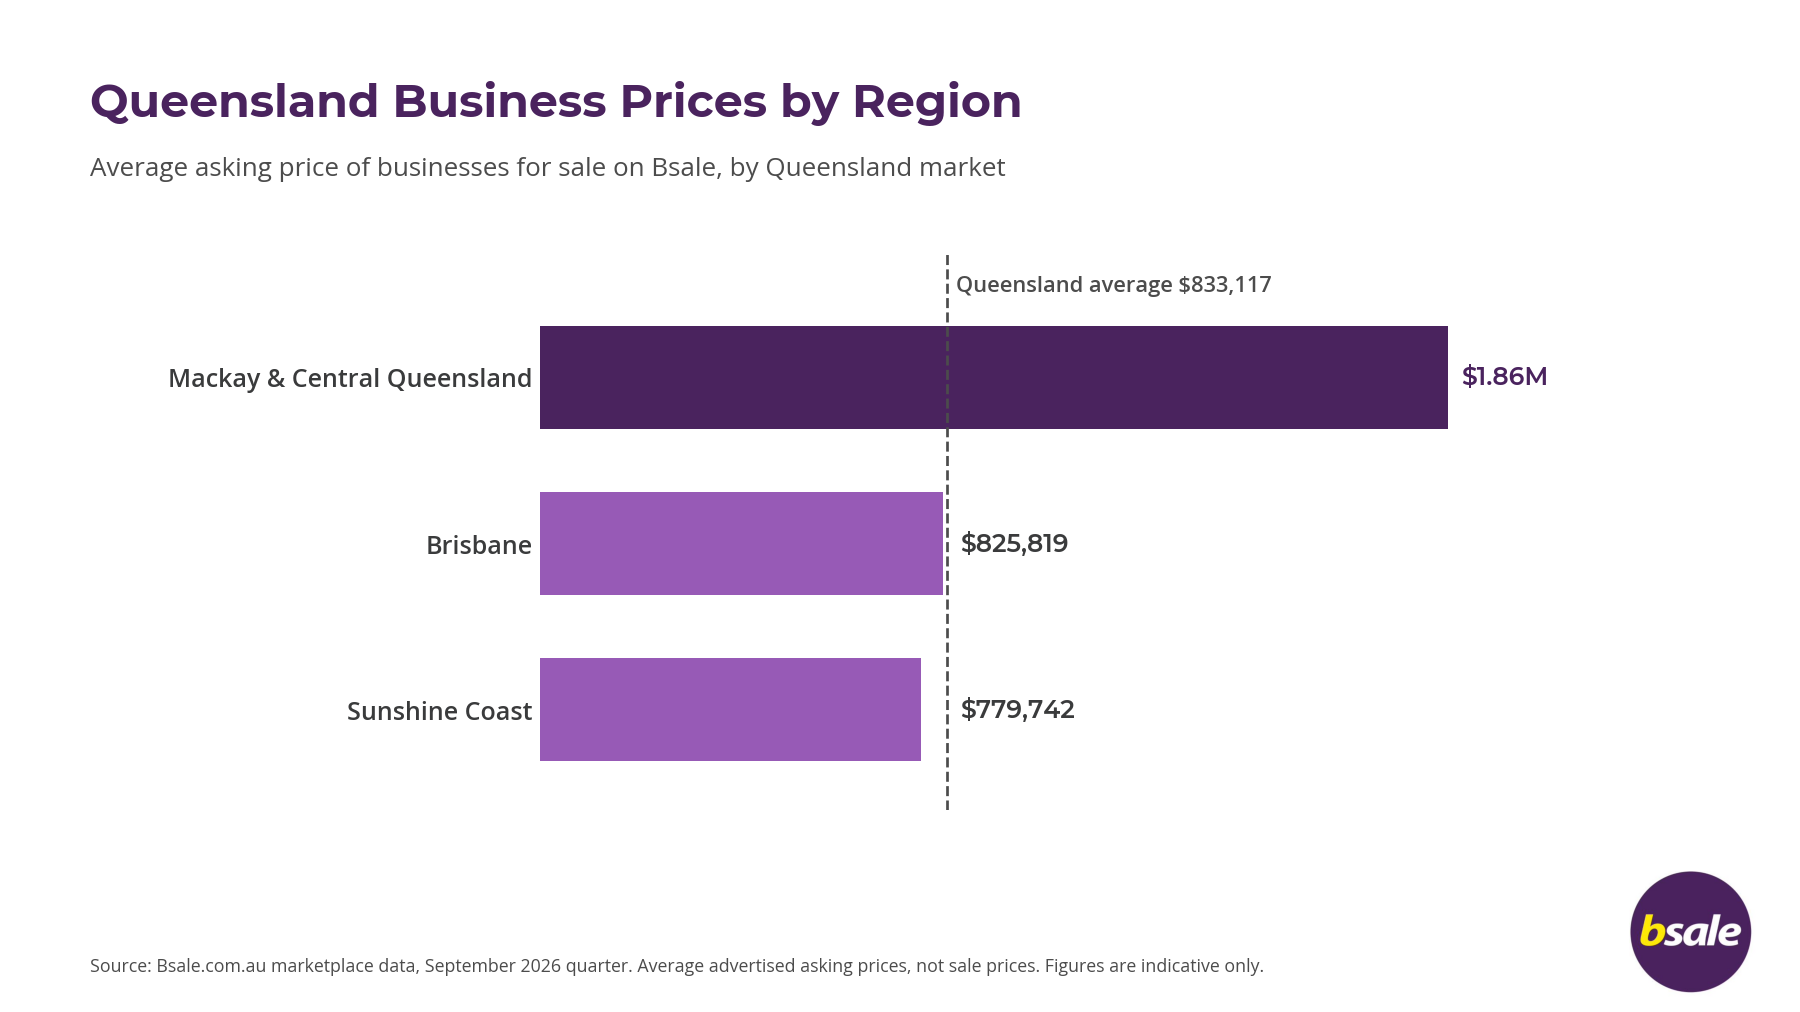
|
Market |
Average asking price (Sep 2026 quarter) |
What you will find |
|---|---|---|
|
$1.86 million |
Mining services, transport and industrial businesses, across more than 150 listings |
|
|
$825,819 |
The second-highest average of the capital cities |
|
|
$779,742 |
A mid-range market with wide choice |
|
|
Among the more accessible regional markets |
Strong buyer interest |
Buyers can also browse Cairns & Far North Queensland and Toowoomba & Darling Downs.
Higher regional averages may partly reflect what the asking price includes, such as plant, machinery, vehicles, stock or freehold property. Always check what a price covers before comparing businesses.
Buyers Want Businesses That Run Without Them
Nationally, buyers on Bsale showed a clear preference for businesses that do not need a full-time owner. Listings advertised as under management drew around 30% more enquiries than average, while remote and home-based listings drew more than twice the average.
How to Buy a Business in Queensland, Step by Step
The buying process in Queensland follows the same broad path as the rest of Australia. Business Queensland's guide to buying a business is a useful overview, along with its advice on deciding whether to buy a business. The differences sit mostly in the state rules covered in the next section.
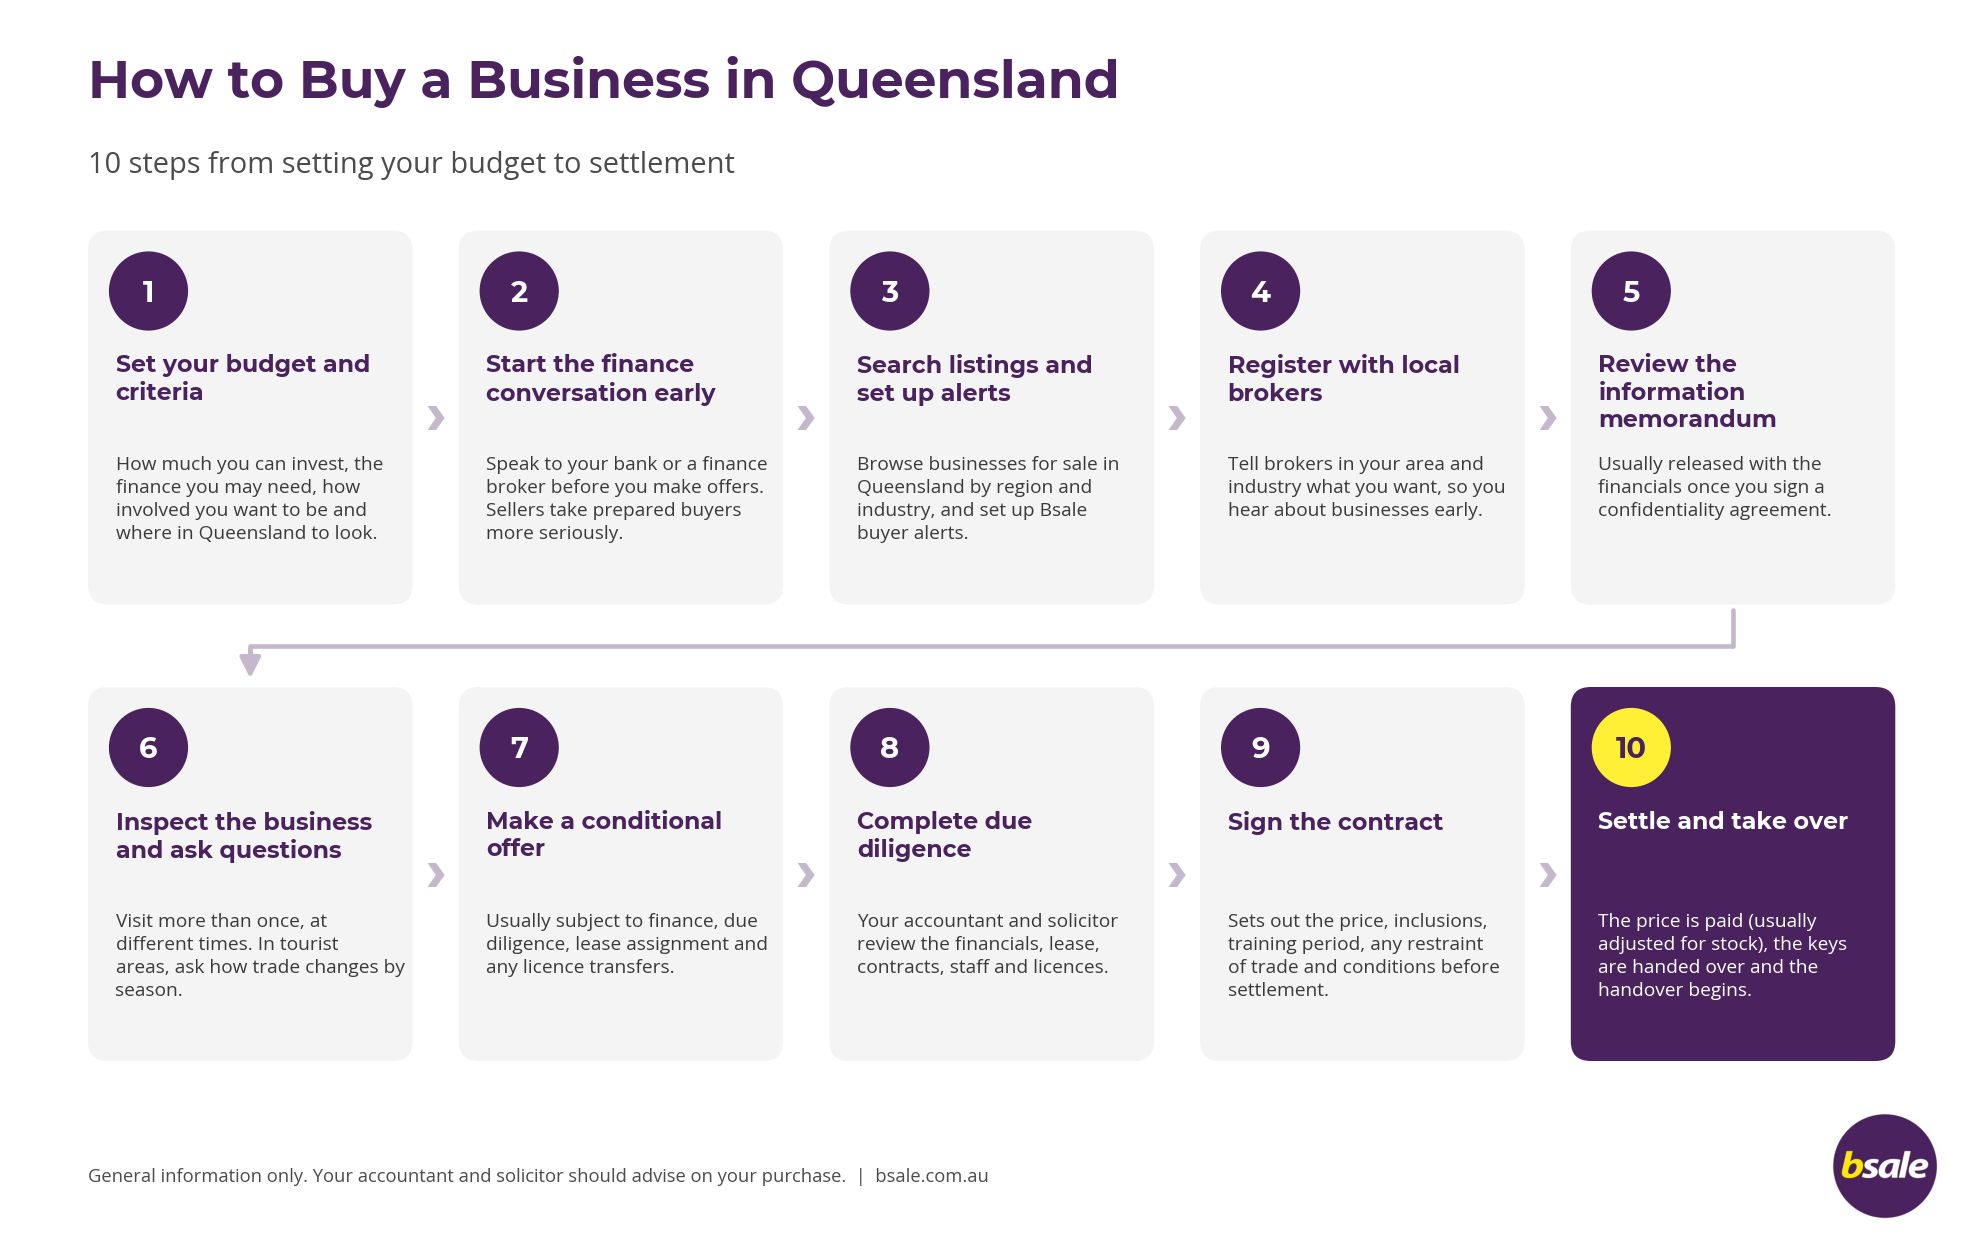
- Set your budget and criteria. Work out how much you can invest, how much finance you may need and how involved you want to be. Decide whether you are looking at Brisbane, the Gold Coast or Sunshine Coast, or a regional centre such as Toowoomba, Mackay, Townsville or Cairns.
- Get your finance conversation started early. Speak to your bank or a finance broker before you start making offers. Buyers on Bsale are increasingly asking about finance and vendor finance, and sellers take prepared buyers more seriously.
- Search listings and set up alerts. Browse businesses for sale in Queensland by region and industry, and set up Bsale buyer alerts so new listings come to you.
- Register with local brokers. Let Queensland brokers in your target area or industry know what you want, so you hear about suitable businesses early.
- Review the information memorandum. Most brokers will ask you to sign a confidentiality agreement before releasing the information memorandum and financials.
- Inspect the business and ask questions. Visit more than once if you can, at different times of the day and week. In tourist areas, ask how trade changes across the seasons.
- Make a conditional offer. Offers are usually made subject to finance, due diligence, lease assignment and any licence transfers.
- Complete due diligence. Have your accountant and solicitor review the financials, lease, contracts, staff and licences. More on this below.
- Sign the contract. A sale of business contract sets out the price, what is included, the training period, any restraint of trade and the conditions to be met before settlement.
- Settle and take over. At settlement, the price is paid (usually adjusted for stock), the keys are handed over and the training or handover period begins.
It also helps to understand common sale terms. A price advertised as WIWO (walk in, walk out) usually includes stock, while a price plus SAV means stock at valuation is added at settlement.
Queensland Rules Buyers Should Know
Several parts of a business purchase are governed by Queensland law. For a legal perspective, see these 10 things to consider before buying a business in Queensland. Your solicitor and accountant should confirm how each applies to the business you are buying, as rules and thresholds change.
Business Broker Licensing
Business brokers selling businesses in Queensland need to be licensed, and the Office of Fair Trading Queensland keeps a public register you can search. See how to tell if a business broker is licensed in QLD.
The broker is usually engaged by the seller. They can guide you through the process, but you should rely on your own accountant and solicitor for independent advice.
Transfer Duty
In Queensland, transfer duty (stamp duty) can apply to business assets such as goodwill, business names, statutory licences and franchise rights, not just land. It is generally based on the higher of the price paid and the dutiable value of the assets, and exemptions can apply.
The Queensland Revenue Office's transfer duty calculator gives an estimate, and its rates page shows the current rates. Foreign buyers may also pay additional foreign acquirer duty. Confirm your obligations with your solicitor or accountant before you agree on the price and how it is split between assets.
Retail and Commercial Leases
For most businesses that do not own their premises, the lease is one of the most important documents in the sale. Many shop leases in Queensland are covered by the Retail Shop Leases Act 1994 (Qld), which sets rules on disclosure and assignment.
The lease usually needs to be assigned to you with the landlord's consent. Check the remaining term, options to renew, rent reviews, outgoings and any make-good obligations. The Queensland Small Business Commissioner can help with some retail lease disputes. See 6 ways a lease agreement can impact your business sale price.
Licences and Registrations
Licences rarely transfer automatically. Allow time in your contract for transfers or new applications.
- Food businesses: cafes, restaurants, takeaways and bakeries generally need a food business licence from the local council. Ask the council early whether the licence can be transferred or a new one is needed.
- Licensed venues and liquor stores: liquor and gaming licences are managed by the Office of Liquor and Gaming Regulation.
- Other regulated businesses: childcare, home care, health, transport, security and trade businesses can need specific licences or accreditations. Check what applies before you commit.
Staff and Employer Obligations
If you take on existing employees, ask how their leave entitlements are treated in the contract, including long service leave, as service with the previous owner may carry over.
As a new employer, you will also need workers' compensation cover through WorkCover Queensland, and payroll tax may apply if your wages exceed the Queensland threshold. Your accountant can confirm the current threshold with the Queensland Revenue Office.
Due Diligence and Finance
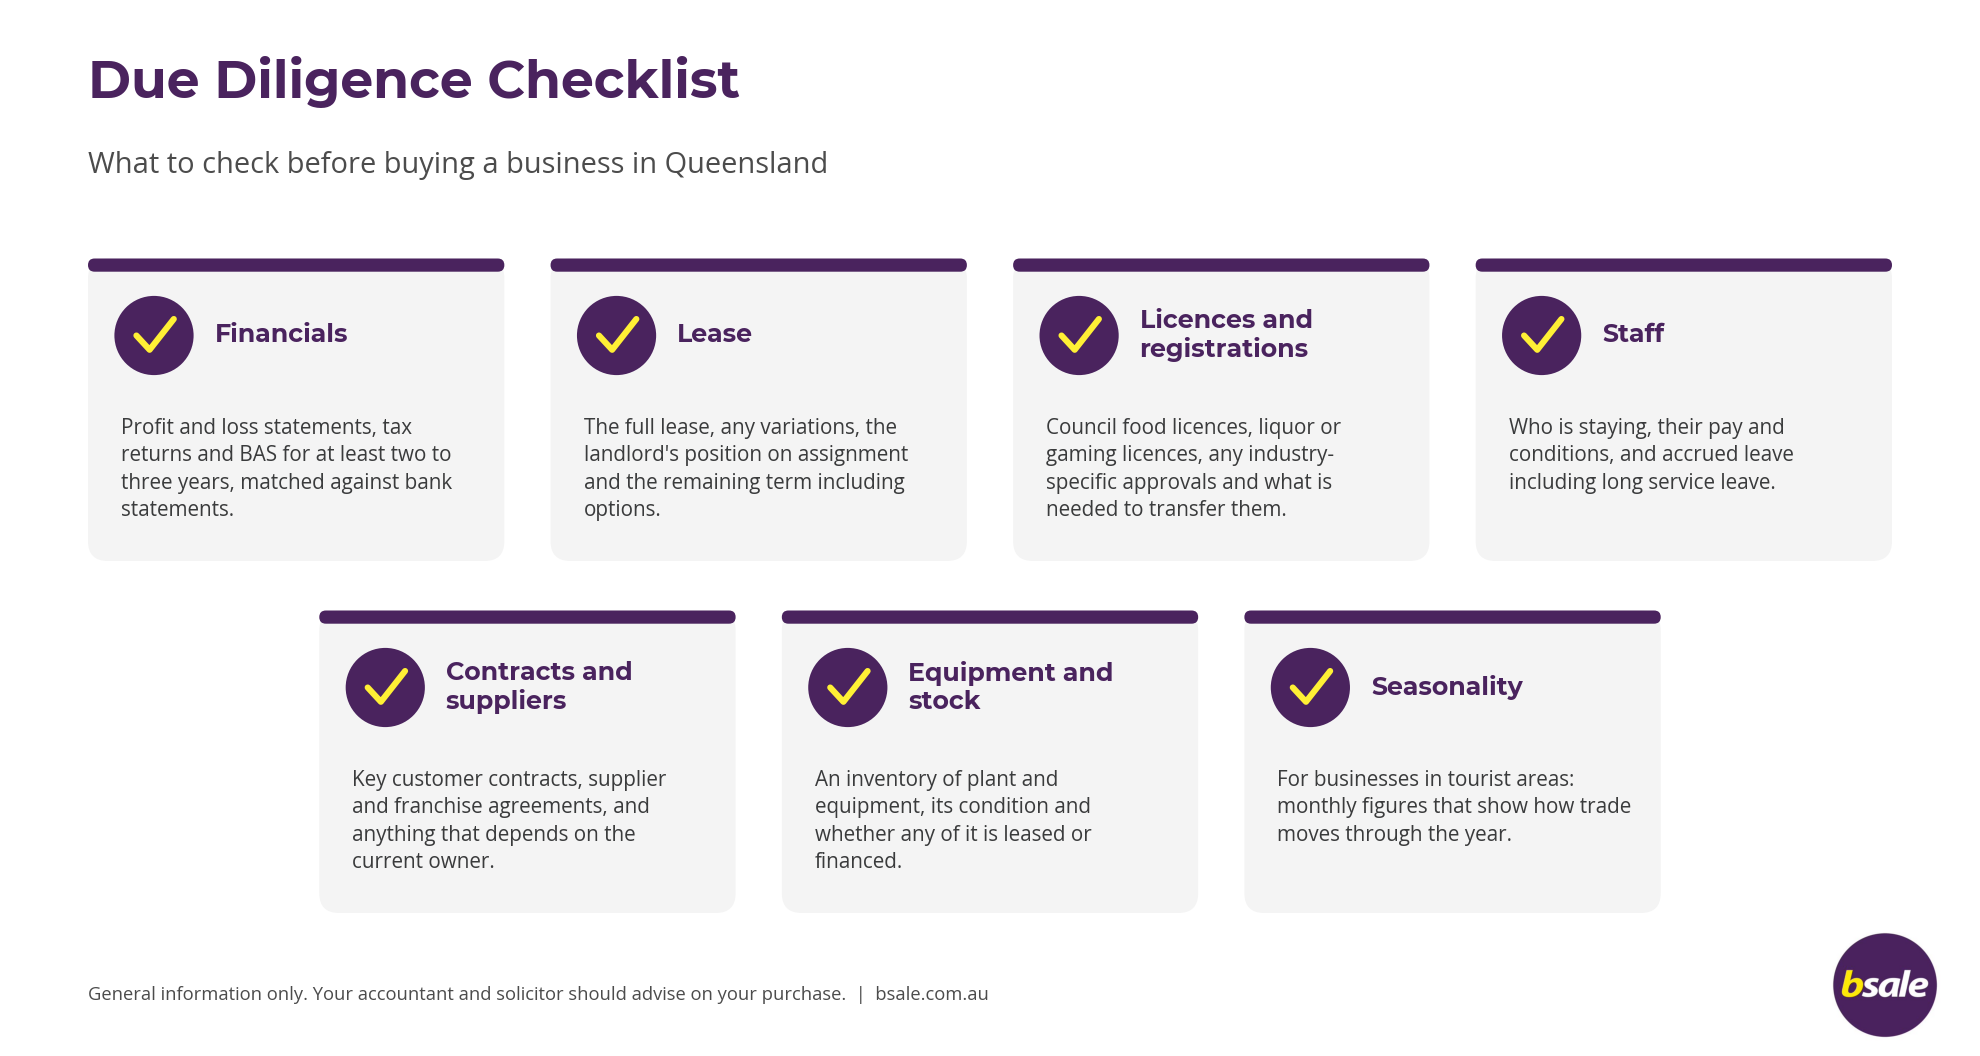
Due diligence is where you confirm the business is what the seller says it is. Brookwater Legal has a detailed checklist for buying a business in Queensland. In Queensland, due diligence usually covers:
- Financials: profit and loss statements, tax returns and BAS for at least two to three years, matched against bank statements.
- Lease: the full lease, any variations, the landlord's position on assignment and the remaining term including options.
- Licences and registrations: council food licences, liquor or gaming licences and any industry-specific approvals, plus what is needed to transfer them.
- Staff: who is staying, their pay and conditions, and accrued leave including long service leave.
- Contracts and suppliers: key customer contracts, supplier agreements, franchise agreements and anything that depends on the current owner.
- Equipment and stock: an inventory of plant and equipment, its condition and whether any of it is leased or financed.
- Seasonality: for businesses in tourist areas, monthly figures that show how trade moves through the year.
The quality of the seller's records matters as much as the numbers themselves. Brisbane broker Dustin Slypen of LINK Business Brokers has seen good businesses held up by poor preparation.
“We know they've got a great business in terms of revenue and profit figures may exist, but if financial records are a mess, accountants can't complete due diligence, and lenders are reluctant to lend,” he said.
He also believes the advisers you choose matter, as deals can become unnecessarily complicated when buyers or sellers use advisers without experience in commercial transactions. For help putting your team together, read the 5 experts every business buyer needs on their team.
At Advantage Business Sales & Valuations on the Sunshine Coast, Stephen Wolff does the detailed work on each sale. As his business partner and wife Dione Mauric puts it, “He makes sure everything is perfect because surprises kill deals.”
Financing Your Purchase
Most buyers combine their own funds with a business loan, and lenders will look closely at the business's records and your experience. Nearly one in five buyers who wrote a message on Bsale in the September quarter asked about finance or vendor finance, up from 13% a year earlier.
Finance can shape which businesses are realistic to buy. Dustin sees the strongest activity in the $300,000 to $800,000 range, where owner-operators can create value through hands-on involvement. Below $200,000, he finds businesses often struggle to attract qualified buyers because securing funding has become harder.
Russell McVey, who founded Business Brokers Network Australia says many buyers now need stronger financial credentials before lenders will support a purchase. Read more about why vendor finance and buy-out options are increasing.
What Queensland Brokers Are Seeing
Bsale's Queensland eMagazine edition featured brokers working across Brisbane, the Sunshine Coast and North Queensland. Their experience offers practical lessons for anyone buying in the state.
Buyers Are Looking for Solid Fundamentals
Russell McVey says buyers have become more selective as wages, operating costs and compliance requirements have risen. A small business that once suited an owner-operator may no longer produce enough income to justify the investment.
“Small industrial businesses that service tradies, all the businesses that service hospitality in the tourist areas. Small businesses that really understand their immediate area and service it. But they've got to be taking over a million dollars a year to be worthwhile,” he said.
In North and Far North Queensland, Susan Butler, principal broker at Beyond 2000, sees service businesses, cleaning companies, transport businesses and established regional hospitality operations drawing strong interest.
“Quality businesses with consistent profits, reasonable rent, and systems that reduce reliance on the owner are particularly appealing,” she said. Owner-dependent businesses, and those with very high rents, declining profits or short lease terms, can be harder to sell, and harder for buyers to finance.
Lifestyle Matters, Especially in the North
Susan has noticed buyers asking different questions than they used to. “Ten years ago, many buyers were focused almost exclusively on profit,” she said. Today, working hours, flexibility and work-life balance come up far more often.
“Our region continues to attract lifestyle-focused buyers, particularly people relocating from southern states who are drawn to the climate, affordability, and lifestyle opportunities,” she added.
If you are moving to Queensland to buy a business, it is worth being clear about the lifestyle you want as well as the return. A business that needs you on site seven days a week may not deliver the change you are after.
Look Beyond the Headline Profit
At LINK Business Brokers in Brisbane, Roland West has sold businesses on behalf of liquidators and banks where the fundamentals were sound despite the financial problems.
“Even though a business may not be profitable, they may still have some value,” he said.
The structure of a deal can also make the difference. Dustin Slypen sold a North Queensland roofing business that ran largely under management, but buyers kept worrying about what would happen if the general manager left. His solution was for the manager to keep a 10 to 20 percent stake in the business. A buyer agreed, the seller achieved their target price, and the business has since kept growing.
“I spoke to the buyer of that business three or four months ago. The business has grown by another 15% on the previous year,” Dustin said.
A Good Broker Works With Both Sides
The broker is engaged by the seller, but experienced brokers know a sale only happens when both parties are satisfied. Roland puts it simply.
“I work for the buyer as much as I do for the seller,” he said. “Without that balance, we don't have a deal.”
Treat the broker as a useful guide to the business and the process, and lean on your own accountant and solicitor for advice on whether the deal is right for you.
Opportunities Ahead
Many long-term business owners are approaching retirement, and their children often have other careers. Dustin believes that is creating a pipeline of established businesses for buyers willing to act.
“No matter how strong or weak a perceived market is, there are always opportunities there,” he said.
Frequently Asked Questions
Is there stamp duty on buying a business in Queensland?
Transfer duty can apply, depending on the assets being bought and how the sale is structured. Get advice from your solicitor or accountant before agreeing on the price and how it is allocated.
Where are businesses most expensive in Queensland?
On Bsale in the September 2026 quarter, Mackay & Central Queensland had the highest average asking price at $1.86 million, driven by mining services, transport and industrial businesses. The Gold Coast was among the more accessible regional markets. Regional prices may include freehold, plant or vehicles, so compare what each price includes.
Can I get finance for a small business purchase?
Often yes, but lenders will look closely at the business's records and your own position. You need to understand that your experience, your assets and the business your buying will impact your lending capacity. Speak to a lender early.
How long does it take to buy a business?
It depends on finance, due diligence, lease assignment and licence transfers. On Bsale, the median time between a business being listed and marked as sold is 202 days, though that reflects the time from listed for sale, to being marked sold.
Start Your Search
Browse businesses for sale in Queensland, or narrow your search to Brisbane, the Gold Coast, the Sunshine Coast, Toowoomba & Darling Downs, Mackay & Central Queensland or Cairns & Far North Queensland. You can also find a broker through Bsale's business brokers directory.
Disclaimer: Statistics are based on Bsale.com.au marketplace data and do not represent the entire Australian business sales market. Listing information is supplied by advertisers and is not independently verified by Bsale. Data may contain errors, duplicates or outdated information. Listings and asking prices may not be directly comparable, including those advertised as WIWO, plus SAV or including freehold property. Asking prices are not confirmed sale prices, and listings marked as sold do not verify completed transactions. Figures are indicative only. This article is general information, not professional advice. Readers should conduct independent due diligence before making business or investment decisions.
Tags: guide brisbane queensland buying a business
About the author
Vanessa Lovie-Yousaf
CEO Bsale Australia
Vanessa Lovie-Yousaf is the CEO and manager of Bsale.com.au, one of Australia’s most trusted business for sale marketplaces since 2000. With 15 ...


